October 9, 2026
Tax Planning for Small Business: 7 Moves to Make Before December 31, 2026
Tax planning for small business before December 31, 2026: seven practical year-end moves covering expenses, equipment, retirement plans, QBI, health insurance, and bookkeeping.
A business owner who waits until filing season has already lost most of the choices that could have affected the 2026 tax bill. By April, the year is closed, equipment purchases are finished, payroll has been reported, and many planning decisions are no longer available.
That does not mean you should spend money just to create a deduction. It means you should review the business now, identify legitimate opportunities, and document decisions before December 31, 2026.
The following checklist is general information for tax planning for small business. It is not a determination of eligibility or a substitute for reviewing your business, entity type, accounting method, income, payroll, and personal tax situation with a qualified tax professional.
1. Review your 2026 profit and loss before year-end
Start with the numbers you already have. Review year-to-date revenue, expenses, owner payments, payroll, estimated taxes, debt, inventory, and cash flow. Then compare the current results with the budget or the same period in 2025.
This review can reveal whether your 2026 profit is higher or lower than expected. It can also uncover missing expenses, duplicate transactions, unpaid invoices, unreconciled accounts, or unusually large changes that need explanation.
Practical step: Prepare a year-end estimate of total 2026 revenue and deductible expenses. Include expected December activity, payroll, retirement contributions, equipment purchases, health insurance, and estimated tax payments.
Documentation caution: Keep the reports used for the estimate, including your profit-and-loss statement, balance sheet, bank reconciliations, payroll reports, loan statements, and explanations for unusual transactions. A forecast is only useful when it is based on complete records.
2. Time income and expenses only within legitimate accounting rules
Timing can matter, especially for a business that properly uses the cash method. In general, cash-method businesses often recognize income when it is received and expenses when they are paid. However, prepaid expenses, inventory, accrual accounting, and other rules can change the result.
Year-end planning should not involve pretending that a transaction happened when it did not. Do not delay a customer payment, prepay an unrelated expense, or alter an invoice solely to manufacture a tax result.
Practical step: Review normal collections and bills with your tax professional. Pay valid 2026 business expenses before December 31 when the expense is real, the business can afford it, and the payment is treated correctly under the business's accounting method.
Documentation caution: Save invoices, receipts, payment confirmations, contracts, and the business reason for significant payments. A credit-card charge, check, or electronic payment should connect clearly to a legitimate business expense.
3. Evaluate equipment purchases, Section 179, and bonus depreciation
If your business needs equipment, technology, furniture, machinery, or certain other business property, December can be a useful time to review the purchase. But buying an item is not automatically the same as placing it in service.
For 2026, the maximum Section 179 deduction is $2,560,000, with a dollar-for-dollar phase-out beginning when qualifying property placed in service exceeds $4,090,000. Section 179 also has business-income limitations and other restrictions.
The IRS also provides a 100% additional first-year depreciation deduction for generally eligible depreciable property acquired after January 19, 2025, under current federal guidance. Eligibility, placed-in-service rules, business use, vehicle restrictions, state conformity, and other limitations must be reviewed.
Practical step: Before ordering equipment, compare Section 179, bonus depreciation, and regular depreciation. Confirm that the asset will actually be ready and available for business use by the applicable 2026 deadline.
Documentation caution: Keep the purchase agreement, invoice, payment record, serial number, date placed in service, percentage of business use, and financing documents. A planned purchase or a deposit may not be enough.
4. Review retirement plan contributions and deadlines
Retirement contributions can support long-term savings while also affecting 2026 tax planning. The right choice depends on the business structure, employee situation, compensation, cash flow, and plan documents.
For 2026, the employee elective-deferral limit for most 401(k), 403(b), governmental 457 plans, and the federal Thrift Savings Plan is $24,500. The regular catch-up contribution for eligible participants age 50 and older is $8,000. The higher catch-up amount for eligible participants ages 60 through 63 is $11,250.
The 2026 defined-contribution annual-additions limit is $72,000, before applicable catch-up contributions. A SEP may allow contributions up to the lesser of $72,000 or 25% of eligible compensation, subject to the applicable rules.
These limits do not mean every owner can contribute the maximum. Employee eligibility, nondiscrimination rules, compensation definitions, payroll timing, and plan design matter.
Practical step: Review 2026 payroll deferrals now. If you do not have a plan, compare options such as a 401(k), SEP IRA, SIMPLE IRA, or profit-sharing arrangement before making a contribution decision.
Documentation caution: Keep the plan document, payroll reports, contribution confirmations, employee notices, compensation records, and evidence that contributions were made according to the plan terms.
5. Review the qualified business income deduction
The qualified business income deduction, often called the QBI deduction, may be available to eligible owners of pass-through businesses. It can apply to certain income from sole proprietorships, partnerships, S corporations, and some trusts and estates.
At a general level, the deduction can be up to 20% of qualified business income. However, the calculation can be affected by taxable income, W-2 wages, qualified property, business type, investment income, owner compensation, and whether the business is a specified service trade or business.
Other deductions can also affect QBI. For example, self-employed health insurance and qualified retirement-plan contributions may reduce the income used in the calculation.
Practical step: Include QBI in your 2026 tax projection, but do not estimate it by applying a simple percentage to gross sales or bank deposits.
Documentation caution: Provide complete business income, expense, payroll, depreciation, health insurance, retirement, and personal tax information. QBI is highly fact-specific and requires professional review.
6. Check health insurance and related benefits
A self-employed individual may be able to claim a deduction for qualifying medical, dental, vision, and certain long-term-care insurance premiums for the owner, spouse, dependents, and potentially a child under age 27. The deduction has earned-income and employer-coverage limitations.
More-than-2% S corporation shareholders require special handling. The S corporation may pay or reimburse health insurance premiums, but the amount generally must be handled correctly on the shareholder's Form W-2 and in the company's records.
If you have an HSA-eligible health plan, 2026 HSA contribution limits and eligibility rules should also be reviewed. The 2026 limits are $4,400 for self-only coverage and $8,750 for family coverage, subject to the applicable requirements.
Practical step: Gather policy statements, payment records, coverage dates, employer-coverage information, reimbursement records, and W-2 details before year-end reporting begins.
Documentation caution: Do not assume that every insurance payment qualifies. Preserve proof of who was covered, who paid the premium, and whether other employer coverage was available.
7. Get the books and records caught up before December
Waiting until April to reconstruct the books increases the risk of missed deductions, incorrect income, poor cash-flow decisions, and incomplete documentation. It can also make it harder to identify payroll, inventory, fixed-asset, and owner-payment problems while corrections are still possible.
Practical step: Reconcile business bank and credit-card accounts, categorize transactions, review unpaid invoices and bills, record fixed assets, verify payroll, check inventory where applicable, and separate personal expenses from business expenses.
If the records are seriously behind, bookkeeping and accounting support may be the appropriate next step before professional tax preparation begins.
Documentation caution: Save receipts and invoices with the business purpose, date, amount, vendor, and payment method. Bank statements alone may not explain why an expense was business-related.
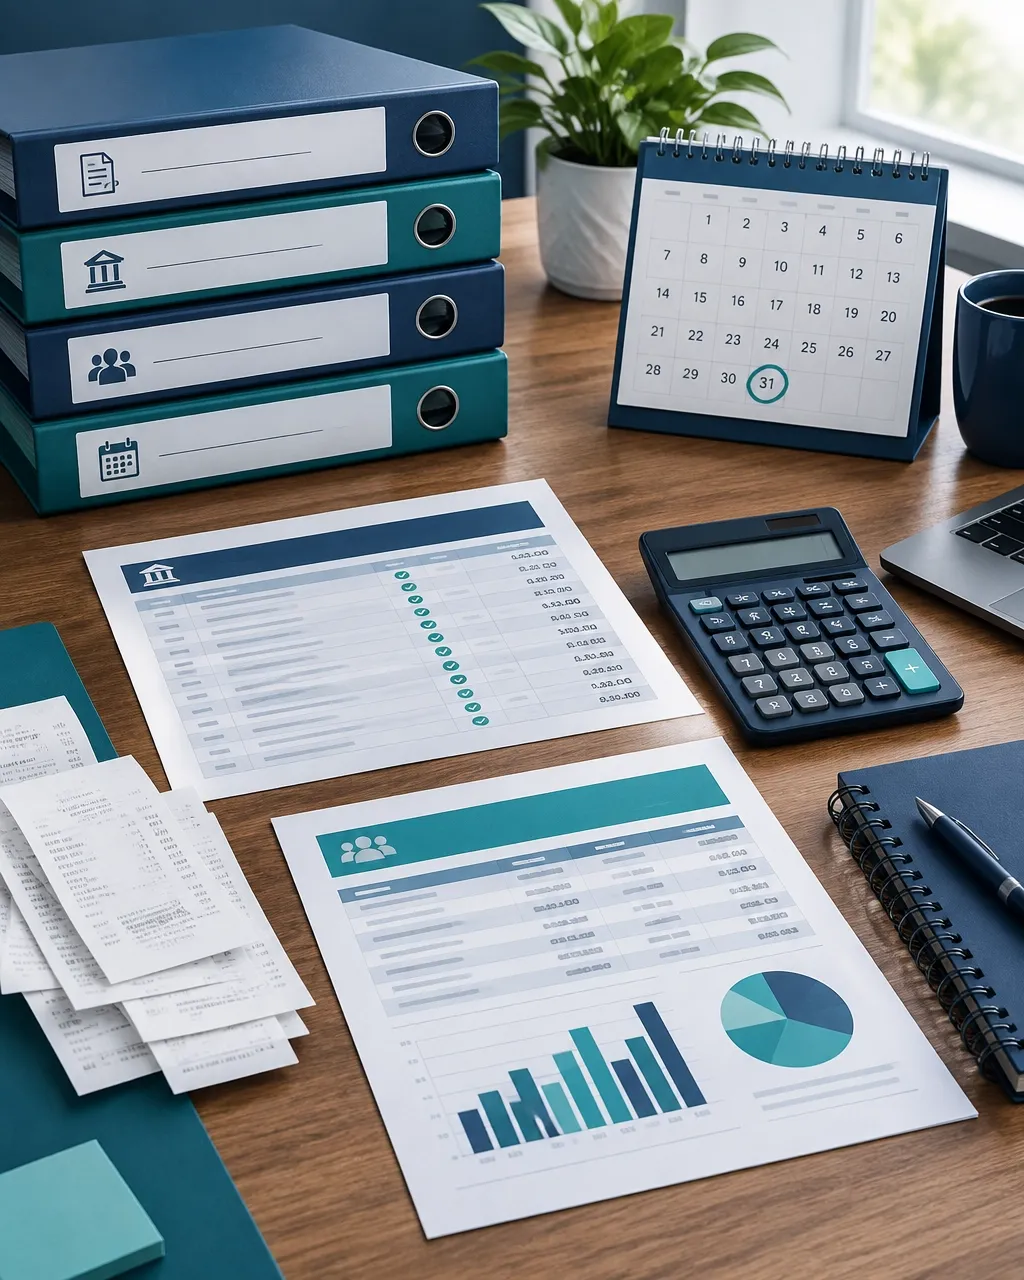
December 2026 checklist
Before December 31, 2026:
- Run a current profit-and-loss and cash-flow review.
- Estimate full-year 2026 income and expenses.
- Reconcile bank and credit-card accounts.
- Review legitimate expenses that should be paid before year-end.
- Confirm whether planned equipment will be placed in service.
- Review Section 179, bonus depreciation, and regular depreciation.
- Check retirement plan contributions and employee requirements.
- Document health insurance and HSA activity.
- Review owner compensation and payroll reporting.
- Gather receipts, invoices, loan records, mileage logs, and asset information.
- Recalculate estimated tax with the year-end changes included.
- Send complete records for professional review before filing season.
Frequently asked questions
Is tax planning for small business only for corporations?
No. Sole proprietors, single-member LLCs, partnerships, S corporations, and other business structures may all benefit from year-end planning. The available deductions and deadlines depend on the entity and the owner's facts.
Should I buy equipment before December 31, 2026 to reduce taxes?
Only if the equipment is genuinely needed, affordable, qualifying property, and placed in service under the applicable rules. A tax deduction generally does not make an unnecessary purchase financially wise.
Can I deduct every expense I pay before year-end?
No. The expense must be legitimate, properly documented, connected to the business, and treated correctly under the business's accounting method. Prepayments and capital purchases may follow different rules.
Does a larger deduction guarantee a better tax result?
No. A deduction can reduce taxable income, but it can also affect QBI, depreciation, cash flow, estimated taxes, state taxes, and future-year deductions. A larger refund is not proof that a return was prepared better.
Conclusion
The best 2026 tax planning decisions are based on accurate books, real business needs, lawful timing, and complete documentation. Do not overstate expenses, create artificial transactions, or make a purchase simply because someone says it is deductible.
Review the numbers now, identify the decisions that still matter, and have the final tax treatment reviewed against your full facts.
Contact Total Tax Pros about year-end planning and tax preparation for your business.
This article is for general educational purposes and is not a substitute for individualized tax advice. Tax laws, limits, forms, and eligibility requirements may change. Confirm current IRS guidance or consult a qualified tax professional before filing.